


How PerCapita Cash Flow Control Unifies Cash, Deposits, Terms, Costs and Safety Buffer

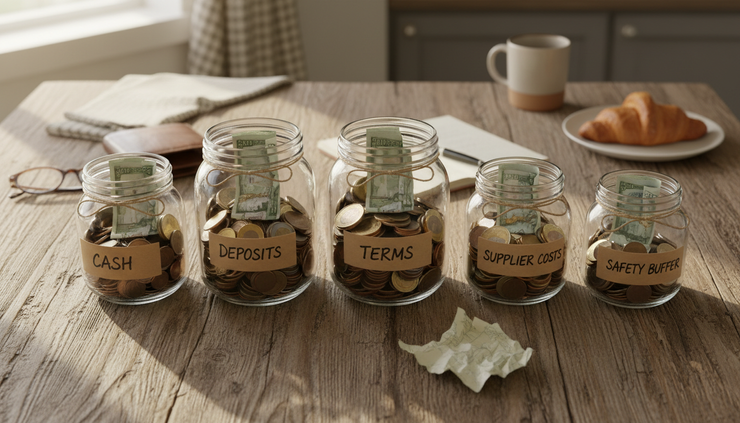
Cash flow trouble rarely starts with one dramatic event. More often, it starts with five ordinary numbers being tracked in five separate places.
There is cash in the bank. There are deposits from customers. There are payment terms that decide when the rest of the money arrives. There are supplier bills that land before, during, or after delivery. Then there is the safety buffer, the money that should not be touched unless something goes wrong.
PerCapita Cash Flow Control brings those pieces into one analysis. Instead of asking, “Do we have enough cash today?”, it asks a better question: How much safe, usable cash do we have per customer, per order, or per unit of work after known obligations are included?
That shift matters. It turns a simple bank balance into a working view of liquidity.
Why cash in the bank does not tell the full story
A healthy bank balance can be misleading. Some of that money may already belong to suppliers. Some may be customer deposits that should fund a specific job. Some may need to stay untouched because payroll, VAT, rent, or a delayed payment is coming.
A bank balance shows what is present. It does not show what is available.
For example, imagine a business has €25 000 in the account on 15/04/2026. On paper, that looks comfortable. Yet the picture changes when the details appear:
Cash item | Amount |
Bank balance | €25 000 |
Customer deposits held for active work | €8 000 |
Supplier invoices due within 14 days | €9 500 |
Minimum safety buffer | €5 000 |
Cash that is genuinely available | €2 500 |
The business does not really have €25 000 to spend. It has €2 500 of flexible cash once commitments are respected.
This is the kind of gap PerCapita Cash Flow Control is designed to expose. It does not treat every euro as equal. It separates cash by purpose, timing, and risk.
That makes it especially useful for businesses with deposits, staged payments, custom work, imported stock, contractor costs, or long supplier lead times. The model also works for service firms, trades, clinics, training providers, workshops, hospitality groups, and project-based teams.
This article is informational only and does not replace financial advice from an accountant or adviser who knows the business.
The five inputs that belong in one analysis
Cash flow control often fails when the inputs live apart from each other. Sales teams know deposits. Operations know supplier costs. Finance knows payment terms. Owners know the safety buffer. The bank knows the current balance.
None of those views is enough on its own.
A unified model brings five inputs together.
Cash available
Cash available starts with bank cash, then removes anything already claimed by real obligations. It should exclude ring-fenced tax money, deposits that fund specific jobs, and any minimum reserve the business has chosen to protect.
A simple version looks like this:
`Available cash = Bank cash - committed costs - protected deposits - safety buffer`
This number is often smaller than expected. That is useful, not discouraging. A realistic number supports better decisions.
Customer deposits
Deposits improve cash flow, but they also create responsibility. A €3 000 deposit is not the same as a €3 000 completed sale if work still has to be done.
Deposits should be linked to the cost of delivery. The question is not only, “How much deposit did we collect?” It is also, “Will that deposit cover the first wave of labour, materials, and supplier payments?”
A deposit that arrives early and covers early costs reduces pressure. A deposit that is too small may leave the business funding the customer’s work before the final invoice is paid.
Payment terms
Payment terms decide the timing of cash. Two customers can create the same revenue but very different pressure.
A customer paying 50% upfront and 50% on completion creates a different cash pattern from a customer paying 100% 30 days after invoice. Both may look profitable. Only one may be easy to carry.
Terms need to be measured alongside work stages, not just invoice dates. If supplier costs arrive in week one and customer cash arrives in week six, the business funds the gap.
Supplier costs
Supplier costs include stock, materials, subcontractors, packaging, logistics, software tied to delivery, and any external cost needed to complete the work.
The key question is timing. Costs that arrive before customer money place a load on cash. Costs that arrive after customer money reduce that load.
Supplier terms can protect or weaken cash flow. A 30-day supplier term may help, but only if customer payments arrive before day 30. If customers pay late, the benefit disappears.
Safety buffer
The safety buffer is the amount the business chooses not to spend during normal trading. It protects against late payments, supplier increases, cancelled work, seasonal demand, equipment problems, and tax timing.
A buffer should not be vague. It needs a number and a rule.
For example:
Keep at least €10 000 untouched at all times.
Keep one month of fixed costs available.
Keep enough to cover the largest supplier invoice due in the next 30 days.
Keep a buffer per active customer or project.
The best rule depends on the business model. What matters is that the buffer is included before decisions are made, not after cash has already been spent.
What the per capita view adds
The phrase “per capita” means per head. In cash flow control, it can mean per customer, per booking, per order, per member, per job, or per delivery unit. The right unit depends on how the business earns money.
A per capita view turns total cash into a practical operating measure.
For a project business, the unit may be one active project. For a training provider, it may be one participant. For a repair service, it may be one job. For a subscription service, it may be one active customer.
This matters because total cash can hide pressure created by growth.
A business with 20 active jobs may have more cash than it had with 10 active jobs. Yet if each job requires upfront supplier spending, the cash pressure per job may be worse. Growth then feels profitable in the sales report but tight in the bank.
A per capita model can show:
Cash available per active customer
Deposit collected per order
Supplier cost due per job
Expected cash gap per delivery unit
Safety buffer required per active commitment
Break-even deposit percentage for new work
That makes the analysis easier to act on.
A simple per capita example
Take a made-to-order furniture workshop. It has:
Measure | Amount |
Active orders | 10 |
Cash available after fixed obligations | €18 000 |
Customer deposits collected | €12 000 |
Supplier costs due before completion | €20 000 |
Required safety buffer | €7 500 |
At first glance, €18 000 available cash looks fine. The per order view says more:
Per order measure | Amount |
Cash available per active order | €1 800 |
Deposit collected per active order | €1 200 |
Supplier cost due per active order | €2 000 |
Safety buffer needed per active order | €750 |
Each order creates a near-term supplier need of €2 000, but only €1 200 has been collected as a deposit. The gap is €800 per order before completion. Across 10 orders, that is €8 000 of pressure.
The workshop may still be profitable. The issue is timing. It needs more cash early, better supplier terms, faster milestone billing, or a larger buffer before accepting more work.
How the unified analysis changes decisions
A good cash model should change behaviour. If it only confirms the bank balance, it adds little value.
When cash, deposits, terms, costs, and buffer sit in one view, everyday decisions become clearer.
Pricing and deposit rules become grounded
Many deposit rules come from habit. A business asks for 20%, 30%, or 50% because that feels normal in its market. A unified analysis tests whether the rule actually works.
If early supplier costs represent 45% of order value, a 20% deposit may be too low. If labour is the main cost and payment arrives quickly, a smaller deposit may be acceptable.
The deposit should match the cash pattern of delivery, not just customer expectations.
A useful question is:
What is the minimum upfront payment needed so this order does not weaken safe cash before the next billing point?
That question connects sales policy to cash reality.
Payment terms stop being a side note
Payment terms often sit at the end of a quote or invoice. In practice, they shape the cash cycle as much as price does.
A €10 000 sale paid in advance may be safer than a €12 000 sale paid late. The higher-price job can still be worth taking, but the business needs to see the cash gap before it commits.
A unified view can compare terms such as:
Customer term | Cash effect |
50% upfront, 50% on completion | Reduces early funding pressure |
30% upfront, 40% milestone, 30% completion | Matches staged work well |
100% invoice after delivery, 30 days | Requires cash to fund the full delivery cycle |
Retainer paid monthly in advance | Gives predictable cash if costs are stable |
The best term is not always the strictest term. It is the term that balances customer trust, market norms, delivery cost, and cash safety.
Supplier negotiations become more specific
Asking suppliers for “better terms” is vague. A unified analysis shows what term would actually help.
For example, if customer milestone payments arrive around day 21, moving a supplier invoice from 14 days to 30 days may remove a cash gap. If imports require payment before shipment, the model may show that customer deposits must rise instead.
This also helps avoid false savings. A supplier offering a small discount for immediate payment may look attractive. Yet if that early payment weakens the buffer, the discount may not be worth the added risk.
Growth decisions become safer
More sales can create more strain when deposits, terms, and supplier costs are out of balance.
A per capita model shows whether each new customer adds cash strength or consumes working cash. That gives a clearer answer to questions such as:
Can we accept five more projects this month?
Do we need a larger deposit for rush work?
Which customer terms are too heavy to carry?
How much supplier cost can we commit before the next payment run?
What level of new orders would push us below the safety buffer?
Growth is easier to manage when each new unit of work has a known cash profile.

Building a practical PerCapita Cash Flow Control model
The model does not need to be complex at the start. A clear spreadsheet can work if the data is kept current and the categories are consistent.
Start with one unit, such as customer, order, or project. Then add the key fields.
Use one row per active commitment
Each active unit should have its own row. For example, each project could include:
Field | Purpose |
Customer or order ID | Links cash to a real commitment |
Total value | Shows revenue expected |
Deposit received | Shows early customer funding |
Next customer payment date | Shows when cash should arrive |
Supplier costs due | Shows cash needed to deliver |
Supplier payment dates | Shows timing pressure |
Work stage | Shows whether billing should happen soon |
Allocated safety buffer | Protects against risk |
Net cash position | Shows whether the unit helps or drains cash |
The net cash position should not be based on revenue alone. It should compare expected incoming cash with outgoing costs and buffer needs over time.
Sort by cash risk, not by revenue
Revenue can distract. A large job may look attractive while creating the biggest cash gap.
Sort active work by cash risk. The riskiest items often have one or more of these traits:
Low deposit compared with early costs
Long customer payment term
Supplier payment due before customer cash
High material or subcontractor cost
Unclear completion date
No room left in the allocated buffer
This view helps decide which conversations need to happen first.
A low-risk project may need no action. A high-risk project may need a milestone invoice, a supplier term change, a delivery schedule update, or a hold on extra spending.
Recalculate before saying yes
The strongest use of the model comes before accepting new work.
Before confirming a new order, enter the expected deposit, supplier costs, dates, and buffer need. Then check what happens to safe available cash.
If the order pushes cash below the buffer, the business has options:
Ask for a larger deposit.
Add a milestone payment.
Shorten the customer payment term.
Move supplier payments to match customer cash.
Delay the start date.
Reduce scope until timing works.
Decline or pause the order.
This turns cash flow from a monthly review into a decision tool.
Common mistakes that weaken the model
A unified cash analysis does not need perfect forecasting. It needs honest inputs and regular updates.
The most common mistakes are simple.
Treating deposits as free cash
Deposits feel helpful because they raise the bank balance. They only help safely when the related delivery costs and refund risk are visible.
If a deposit must fund a specific job, label it that way. Do not let it disappear into general spending without tracking the remaining cost to deliver.
Ignoring late payments
Quoted payment terms are not always real payment behaviour. If customers often pay 10 days late, build that pattern into the model.
A term of 30 days may behave like 40 days. That difference can matter when supplier bills are due on day 14 or day 30.
Setting the buffer once and forgetting it
The right buffer changes with order size, supplier exposure, seasonality, and fixed costs. A business taking larger projects may need a larger reserve even if monthly revenue is rising.
Review the buffer when the business changes shape, not only when cash gets tight.
Mixing profit with cash
Profit measures value created. Cash measures timing and survival. A profitable order can still create a cash shortage if costs arrive too early.
Both measures matter. They answer different questions.

What good control looks like
A healthy cash system gives clear answers before pressure builds.
It should show how much money is safe to use, which deposits are tied to which work, when customer money should arrive, which supplier costs are coming due, and how much buffer must stay protected.
PerCapita Cash Flow Control brings those questions into one frame. The value is not in a complicated formula. The value is in seeing each customer, order, or project as a cash event with timing, cost, and risk attached.
When the model works, the business can say yes with more care, set deposits with more confidence, negotiate terms with clearer reasons, and protect its buffer before the bank balance becomes a warning sign.
The practical next step is simple: choose the unit that best matches the work, list every active commitment, and calculate the safe cash position per unit. Once that number is visible, cash decisions become much easier to make.
Effective cash flow management can involve tracking multiple customers, projects and payment milestones. PerCapita Cash Flow Control provides a focused starting point: assessing the cash impact of a specific commitment using available cash, customer deposits, payment terms, supplier costs, other upfront costs and a safety buffer.
Before accepting your next order, test its cash impact. Enter your assumptions in PerCapita Cash Flow Control and explore how deposits, costs and payment timing change the picture.
TRY THE FREE CASH PREVIEW → PerCapita Cash Flow Control


Comments